MSS: the one-page cover sheet when a real estate broker arranges your loan
C.A.R. Form MSS (Revised 12/23) is the Mortgage Loan Disclosure Statement Substitute. When a DRE-licensed broker arranges a home loan and gives you the federal Loan Estimate, this page plus your signed Loan Estimate replace the state’s longer Mortgage Loan Disclosure Statement.
The 10-year-old version
When you buy a toy online, the store sends a price sheet: what it costs, shipping, tax. California has its own price sheet for loans arranged by real estate brokers. The federal government has one too, called the Loan Estimate. Two sheets saying the same thing is silly, so California says: if the broker gives you the federal one, staple this one-page note on top, you both sign, and that is enough. The note also says: this price sheet is not a promise to lend, and here is how to check the broker’s license.
Example: Anh Minh (buyer) is buying 1234 Example Lane, San Jose, CA 95100. His loan is arranged by a broker with a DRE license. He gets a Loan Estimate for a $960,000 first loan. The broker hands him the MSS. Both sign the MSS and the Loan Estimate. That covers California’s disclosure rule.
Who signs it, when to use it, when not to
Who signs
The borrower (buyer), and the real estate broker with its DRE license number, plus the licensee who arranged the loan (“By”, with DRE number).
Use it when
A DRE-licensed broker (or its loan officer) negotiates a federally regulated residential loan and gives a TRID Loan Estimate: first lien $30,000 or more, or junior lien $20,000 or more (DRE advisory, 2015).
Do NOT use it
When you borrow straight from a bank, credit union or a DFPI-licensed lender: they give the Loan Estimate, but this DRE broker form is not part of it. For business-purpose, private or hard-money loans with no Loan Estimate: the broker uses the full Mortgage Loan Disclosure Statement (DRE RE 882, or RE 885 for non-traditional loans). It is never a loan approval.
Deadline
The Loan Estimate is due within 3 business days after your application (federal TRID rule). Without the LE route, the state disclosure is due within 3 business days after a completed written application, or before you become obligated, whichever comes first (B&P Code §10240).
Walk through the form, line by line
It is one page. Four parts. The example broker and borrower are filled in blue.
Top
Who is the broker / arranger of credit
From the actual C.A.R. form. Blue text = example fill-in. Yellow = the part to read. Swipe sideways on a phone.
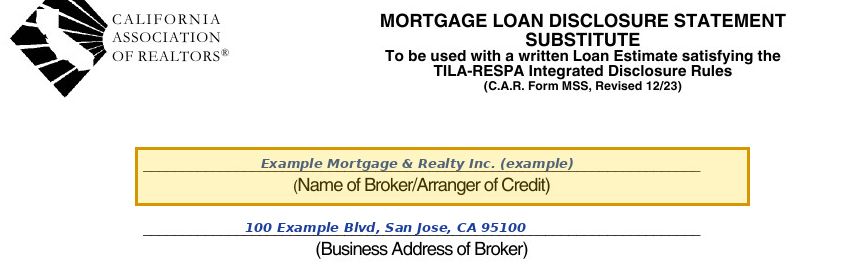
The title says it all: a substitute, to be used with a written Loan Estimate that satisfies the TILA-RESPA Integrated Disclosure (TRID) rules. Under it go the name and business address of the broker arranging the loan. That is the company with the DRE license, not the bank that funds the loan.
Example: Example Mortgage & Realty Inc., 100 Example Blvd, San Jose, CA 95100. The Loan Estimate should show the same broker name and an NMLS number.
Property + the Loan Estimate
Which property, and “not a loan commitment”
From the actual C.A.R. form. Blue text = example fill-in. Yellow = the part to read. Swipe sideways on a phone.
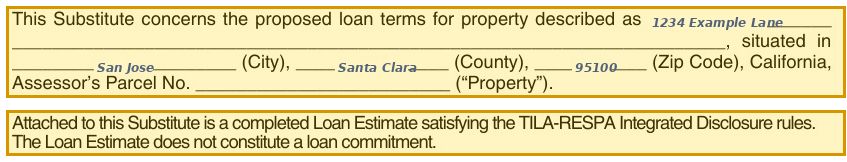
The MSS names the property (address, city, county, zip, APN). Then the two key sentences: a completed Loan Estimate is attached, and the Loan Estimate does not constitute a loan commitment. A Loan Estimate is a price quote. Approval comes later, after underwriting and appraisal.
Example: 1234 Example Lane, San Jose, Santa Clara County, 95100. Anh Minh’s LE shows a $960,000 loan. That does not mean he is approved for it.
Different from the full MLDS (RE 882): the MLDS lists every cost itself across several pages. The MSS lists none; the numbers live in the attached Loan Estimate.
License check + why it must be signed
Check the license, then sign both
From the actual C.A.R. form. Blue text = example fill-in. Yellow = the part to read. Swipe sideways on a phone.
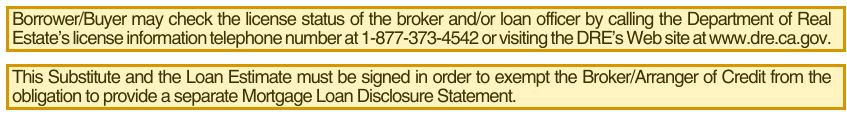
The form gives the DRE license line, 1-877-373-4542, and www.dre.ca.gov, so you can check the broker and loan officer. Last sentence: the MSS and the Loan Estimate must both be signed, or the broker is not excused from giving the separate Mortgage Loan Disclosure Statement.
Example: Anh Minh looks up the broker on the DRE site and the loan officer on NMLS Consumer Access. Both show active. Then he signs.
Signatures
Borrower, broker, and the licensee who arranged it
From the actual C.A.R. form. Blue text = example fill-in. Yellow = the part to read. Swipe sideways on a phone.
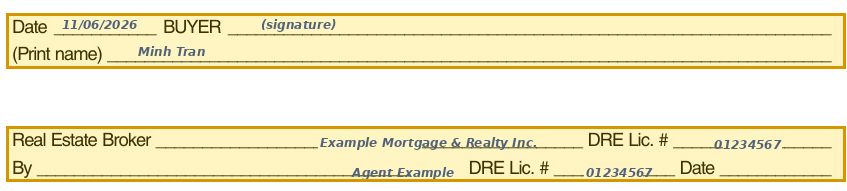
Date and borrower signature with printed name, then the real estate broker and its DRE license number, then “By” the licensee who arranged the loan, with their DRE number and date. The broker keeps signed copies for 3 years (B&P §10240).
Example: 11/06/2026, Minh Tran. Example Mortgage & Realty Inc., DRE 01234567. By Agent Example, DRE 01234567 (example numbers).
x
x
▾
▾
▾
$
x
—
x
What people get wrong
“I got a Loan Estimate, so I’m approved.” The MSS says it in plain words: the Loan Estimate does not constitute a loan commitment.
“The MSS is my loan application.” No. It is a one-page cover disclosure. The application (Form 1003) is separate.
“Everybody gets an MSS.” Only when a DRE-licensed broker arranges the loan. Borrow straight from a bank and you will never see one.
“If I sign the Loan Estimate, I’m locked in.” Signing only confirms you received it. You can still walk and shop.
“My agent can arrange my loan, any agent.” Arranging residential mortgage loans needs a DRE license plus an NMLS loan-originator endorsement. Check both before you sign.